



Most businesses think about receivables and payables in simple terms. Receivables are money customers owe the business, and payables are money the business owes to vendors, suppliers, contractors, lenders, or other parties. That basic definition is useful, but it leaves out the part that causes the most trouble.
The difference between receivables vs payables matters most when a business has to decide when revenue and expenses should be recorded. A customer may owe you money before any cash arrives, and a supplier may be owed money before you pay the bill. In both cases the transaction has to land in the right period so the financial statements reflect what actually happened.
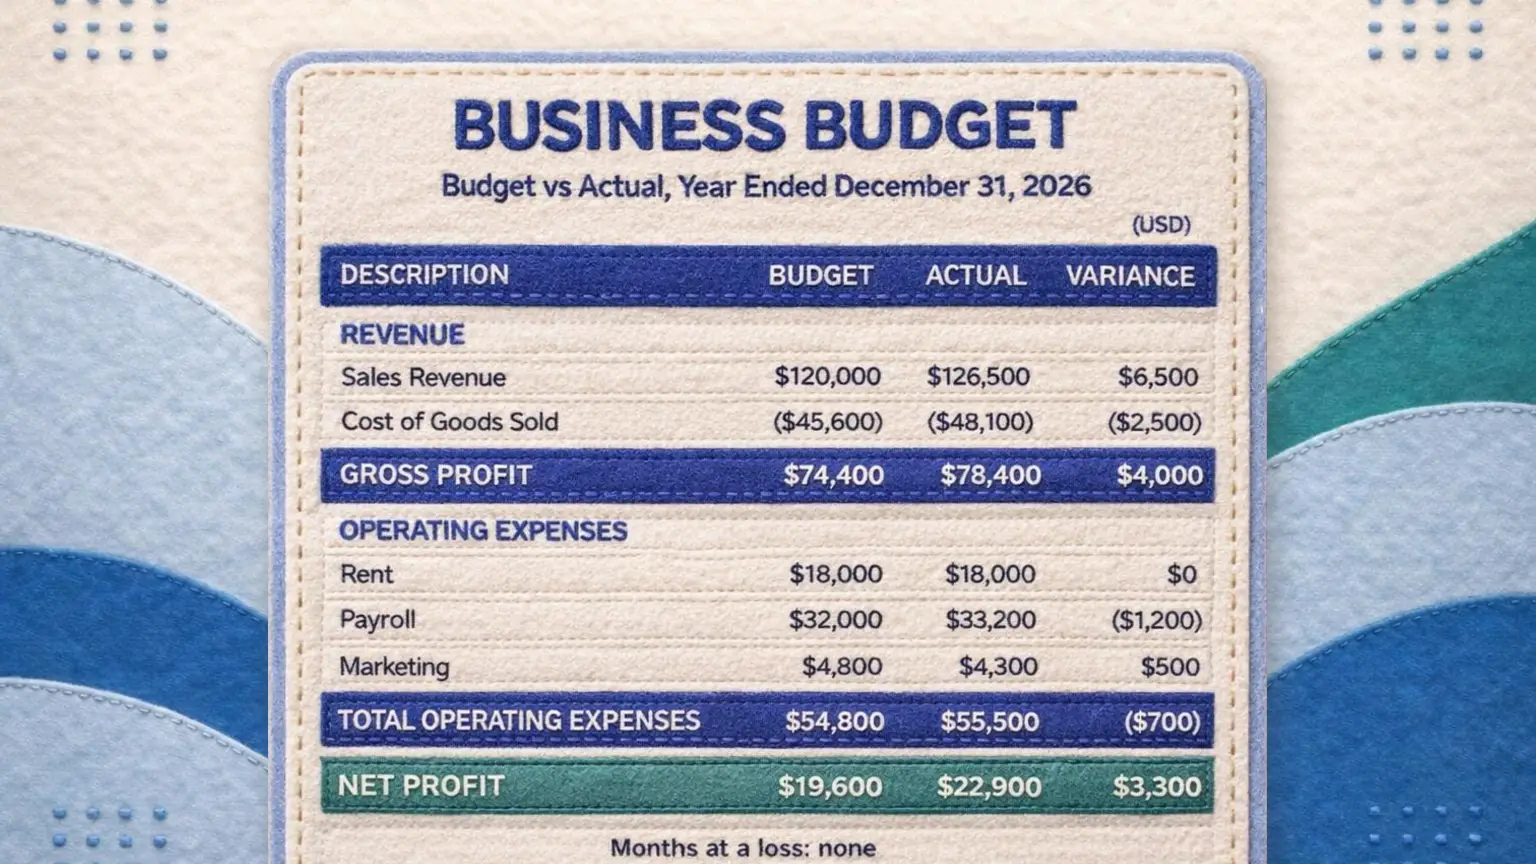
That is why receivables and payables matter well beyond basic bookkeeping. They shape revenue, expenses, profit, working capital, budgeting, cash flow, and month-end reporting, and when they are handled incorrectly a business can look more profitable, less profitable, more liquid, or more stable than it really is.
Key Takeaways
- Under accrual accounting, revenue is recorded when earned and expenses when incurred, regardless of when cash actually moves.
- An invoice creates a receivable, but revenue should only be recognized once the promised goods or services have been delivered.
- A customer paying upfront for a 12-month subscription does not mean all that revenue belongs in the month the cash arrived.
- Supplies received and used in March count as March expenses even when the vendor is not paid until April.
- Treating every invoice as revenue overstates income, and a customer unlikely to pay may require an allowance for doubtful accounts.
Why The Distinction Matters
Receivables and payables sit on opposite sides of the business, with receivables representing amounts flowing toward the company and payables representing amounts flowing away from the company.
Accounts receivable represents money owed to the company, and accounts receivable usually appears when a business provides goods or services before collecting payment from the customer. Accounts payable represents money the company owes to others, and accounts payable usually appears when the business receives goods or services before paying the vendor for those goods or services.
The central question for receivables and payables is not only whether money is coming in or going out but also when the business earned the revenue or incurred the expense. Cash movement and accounting recognition are not always the same thing, and the timing of recognition depends on what was delivered, what was received, and which accounting period the transaction belongs to. A business may send an invoice today and still be required to wait before recognizing all of the revenue on that invoice, and a business may receive a vendor bill next month and still be required to record the expense in the current month.
A software company that sells a 12-month subscription provides a common example of the timing problem. The customer may pay upfront, but the software company has not delivered all 12 months of service on the first day of the subscription. The cash may arrive immediately, while the revenue is usually recognized over time as the service is provided to the customer. When the software company records all of the subscription revenue at once, the first month appears stronger than the first month should appear, and the following eleven months appear weaker than those months should appear.
The same timing issue arises with payables. A business might receive supplies in March and pay the vendor for the supplies in April. When the supplies were used in March, the expense for the supplies belongs in March, and recording the expense in April would make March appear too profitable and would make April appear less profitable than April actually was.
Timing Versus Cash
Cash-based thinking treats cash received as revenue and cash paid as expense, and accrual accounting does not follow that approach. Under accrual accounting, revenue is recorded when the revenue is earned rather than when cash is collected, and expenses are recorded when the expenses are incurred rather than when cash is paid.
The accrual approach is the point at which receivables vs payables becomes more than a balance sheet comparison. Receivables often connect to revenue recognition because receivables represent money expected from customers, and payables often connect to expense recognition because payables represent obligations to vendors or suppliers. Neither receivables nor payables should be recorded mechanically without a review of the underlying transaction, and cut-off problems of this kind are exactly what month-end close controls are designed to catch.
A receivable does not automatically mean that revenue has been fully earned, and a payable does not always mean that an expense should be recognized all at once. The person who keeps the books is expected to understand the contract, the delivery terms, the service period, and the timing of the benefit before recording either a receivable or a payable.
Receivables: How Revenue Recognition Works
Accounts receivable is usually created when a business bills a customer before receiving payment, although billing a customer is not always the same as earning revenue. Revenue recognition depends on a separate question, which is when the business actually delivered the goods or services promised to the customer.
For a simple sale, the recognition question is usually straightforward, because a customer buys a product, the product is delivered, and the business records the revenue. Many transactions are more involved than a simple sale, since a business may bill in advance, deliver services over time, offer bundled products, include warranties, or require customer acceptance before the sale is complete.
Companies run into problems when invoicing is confused with revenue recognition. An invoice may create a receivable, but the existence of an invoice does not always mean that the revenue on the invoice should be recognized immediately.
A business may, for example, send an invoice for a project milestone before the milestone has actually been completed, and in that situation the receivable may need different treatment until the work for the milestone is performed. A company may also bill a customer before shipping goods, and when control of the goods has not transferred to the customer, recognition of the revenue may need to wait until control transfers.
Receivables also affect how a company evaluates collectibility. When a customer is unlikely to pay, the company may need to evaluate whether the revenue should be recognized at all and whether an allowance for doubtful accounts is needed for the receivable. A receivable may appear on the books even though not every dollar of the receivable will eventually become cash.
Common Receivable Pitfalls
A common receivable mistake is the treatment of every invoice as revenue, which can overstate income in periods when the business has not fully delivered what the business promised to the customer.
Another receivable mistake is the omission of customer acceptance terms from the recognition decision. When a contract states that the customer must approve delivery before the sale is complete, revenue from the contract may need to wait until the customer approval is given.
Bundled contracts create a further source of receivable errors. When a sale includes multiple products or services, the transaction price may need to be allocated across each product or service in the bundle, and recognizing the full transaction price at once can distort revenue when part of the obligation will be delivered in a later period.
Collectibility is an additional receivable issue for many businesses. When customers often dispute invoices, delay payment, or request credits, the business needs a process for reviewing receivables and adjusting the allowance for doubtful accounts, because without that process accounts receivable can make the company appear stronger than the company really is.
Payables: How Expense Recognition Works
Accounts payable is created when a business owes money to another party, which often happens when the company receives goods or services before making payment for those goods or services.
Payables do not always tell the full expense story, in the same way that receivables do not automatically equal revenue. Expense recognition focuses on when the business incurred the cost and when the business received the benefit, and when goods or services are received in one period and paid for in another period, the expense usually belongs in the period in which the goods or services were used.
A company may, for example, receive inventory, office supplies, consulting work, advertising services, or contractor support before the vendor invoice arrives. When the benefit of those goods or services belongs to the current period, the business may need to accrue the expense for the current period even though no vendor bill has been received.
Accrued expenses are especially important during the month-end close. When expenses are missing from a period because vendor invoices have not yet arrived, profit for that period can appear artificially high, and when the invoices arrive in the following period, expenses for the following period can appear unusually high. The result is uneven reporting that does not reflect how the business actually performed in either period.
Matching Principle In Practice
The matching principle states that expenses should be recorded in the same period as the revenue that the expenses helped generate, and the matching principle is one of the main reasons that payables need careful review at each period end.
Payroll is a common example of the matching principle in practice. Employees may earn wages in December and receive payment for those wages in January, and the wage expense still belongs in December because December is the month in which the work was performed.
Insurance provides another example of the matching principle. When a business pays for a full year of insurance coverage upfront, the entire insurance payment should not necessarily be treated as one month’s expense, and the cost of the insurance policy is usually spread across the policy period because the benefit of the coverage lasts for the full year.
Vendor bills can also create timing issues under the matching principle. A supplier may deliver goods in March and send the invoice for those goods in April, and when the goods were received in March, the business may need to record the payable and the related expense in March.
Payables also require estimates in some situations. When a company knows that a service was received but does not yet know the final invoice amount for the service, the company may need to accrue a reasonable estimate of the expense, and the estimate can be adjusted later when the final invoice arrives.
Practical Rules For Owners And Bookkeepers
Receivables and payables are easier to manage when the person who keeps the books follows a consistent process for both receivables and payables at each period end.
For receivables, each invoice should be tied back to the customer contract, the delivery record, the service period, or other support showing when the revenue was earned, which helps prevent revenue from being recorded too early or too late. For payables, each vendor obligation should be tied to evidence that the goods or services were received, and that evidence may include purchase orders, receiving reports, vendor contracts, timesheets, or internal approvals.
Customer deposits also require careful treatment. When a customer pays before the business delivers the product or service, the customer payment may need to be recorded as a liability until the business fulfills the obligation to the customer. The same approach applies to prepaid expenses, since a payment made to a vendor upfront for something that benefits future periods may need to be spread across those future periods instead of being expensed immediately.
The purpose of these practices is that receivables should reflect valid claims to future cash, payables should reflect valid obligations to others, and revenue and expenses should be recorded in the correct period based on what actually happened in the business.
Checklist For Month-End
A practical month-end process can prevent many receivable errors and payable errors before the books for the period are closed.
- Match customer invoices to contracts, delivery records, service logs, or acceptance terms.
- Review deferred revenue schedules for upfront payments or partially delivered services.
- Confirm which goods and services were received before month-end, even if invoices have not arrived.
- Accrue expenses for vendor work completed during the period.
- Review receivables for collectibility, disputes, credits, and doubtful accounts.
- Check customer deposits and prepayments to make sure they are not being treated as revenue too early.
- Review intercompany receivables and payables for timing mismatches.
A month-end checklist of this kind keeps the review of receivables vs payables from becoming a guessing exercise during the close, and the checklist gives the business owner and the bookkeeper a repeatable method for reviewing timing issues before the financial statements are finalized.
Communication With The People Who Sell And Buy
The bookkeeper should not be the only person in the business who understands how receivables and payables affect the books.
The people who sell for the business, who are often the owner, focus on signed contracts, customer payments, and closed deals, while the people who buy for the business focus on vendor pricing, purchase timing, and invoice approval. Both groups influence accounting outcomes even though neither group is responsible for preparing the financial statements.
A signed contract does not necessarily mean that revenue can be recognized immediately, and a vendor invoice may not be the only evidence needed to record an expense. A delayed approval can affect payables, and a customer acceptance clause can affect receivables, so these contract and approval details carry accounting consequences for the business.
A short conversation with the people who sell and the people who buy can reduce errors. The people who sell can be shown when a receivable can be recorded and when revenue can be recognized, and the people who buy can be shown when a payable should be recorded and when an expense should be accrued.
Real examples from the business are the most effective material for these conversations, such as what happens when a customer pays 50% upfront, what happens when a vendor delivers part of an order, and what happens when a service contract covers several months. Examples drawn from the business help people outside the bookkeeping function understand why timing matters to the financial statements.
When Receivables Vs Payables Gets More Complicated
Some transactions are straightforward to record, while other transactions require judgment from the person who keeps the books.
Consignment sales, barter transactions, customer deposits, extended warranties, rebates, discounts, retainers, and milestone billing can all complicate receivables and payables. Transactions of this kind often require the owner or the bookkeeper to look beyond the invoice and understand the substance of the transaction.
Revenue may, for example, depend on customer acceptance, on delivery of future services, or on achievement of a performance milestone, and in those cases the business may need to delay some or all of the revenue until the obligation to the customer is satisfied.
Payables can be equally complex, because a vendor may provide a discount, issue a credit, dispute a charge, or deliver only part of an order. The owner or the bookkeeper is then required to determine what was actually received from the vendor and what amount should be recorded as a payable.
Mergers and acquisitions make the receivables and payables review more difficult still. When a company acquires another business, the acquiring company inherits receivables with different customer risks and payables with different payment cycles, and an early review of the acquired receivables and payables helps prevent surprises in cash flow, working capital, and post-acquisition reporting.
Controls That Work
Effective controls over receivables and payables do not need to be complicated, but the controls do need to be applied consistently from one period to the next.
For receivables, documentation that supports revenue recognition should be required, and that documentation may include contracts, order details, shipment records, service logs, customer acceptance records, or billing schedules. For payables, evidence that goods or services were received should be required before accruals are released or payments are approved, and that evidence may include receiving records, purchase orders, approved invoices, or signed service confirmations.
Larger companies may use accounting software or ERP systems to connect billing, purchasing, receiving, and reporting. Smaller companies may use simpler systems, and smaller companies still need clear review steps for receivables and payables at each period end.
The highest-risk items deserve the most attention during the review. Large customer contracts, upfront payments, vendor credits, disputed invoices, and unusual transactions should be reviewed carefully, and while small routine items can usually follow a standard process, unusual transactions should not be pushed through the close without supporting documentation.
How To Keep Receivables And Payables Accurate
Receivables vs payables is not only a comparison between money owed to the business and money the business owes to others, because receivables and payables also raise a timing issue that affects how revenue and expenses appear on the financial statements.
The most important rule is that an invoice does not always equal recognition. A customer invoice does not automatically mean that revenue has been earned, and a vendor bill does not always mean that the related expense belongs entirely in the current period.
Accurate accounting depends on the underlying transaction, including whether the business delivered the product or service, whether the customer received control or benefit, whether the company received goods or services from a vendor, and which period the benefit belonged to.
When those points are settled consistently, receivables and payables become more useful to the business, because receivables and payables then show what the business is owed, what the business owes, how cash may move, and whether revenue and expenses are being recorded in the correct period.
That kind of discipline makes month-end close cleaner, financial reports more reliable, and the decisions you make from those reports easier to trust.