





The short answer is yes. Cost of goods sold is an expense in the plain sense that it reduces profit. The reason anyone asks the question at all is that it does not behave like the other expenses on the income statement, and no accounting package will stop you putting a cost in the wrong place.
What follows sets out where cost of goods sold is reported, the test that separates a direct cost from an overhead cost, the costs that genuinely sit on the line, and what a single misclassified cost does to the reported margin.
Key Takeaways
- Cost of goods sold is an expense, and cost of goods sold is reported above gross profit rather than grouped with operating expenses below gross profit.
- The test is whether the cost would still be incurred in a period in which nothing at all was sold, because a direct cost varies with volume and a fixed overhead cost does not.
- Cost of goods sold equals beginning inventory plus purchases during the period minus ending inventory, so cost of goods sold is determined by what was sold rather than by what was purchased.
- A service business reports the same category under the caption cost of services or cost of revenue.
- Misclassifying a single cost changes gross margin without changing net income at all, which is the reason the classification matters even though the bottom line is unaffected.
Presentation on the income statement
A multi step income statement reports cost of goods sold immediately beneath revenue, and the subtotal reported between cost of goods sold and operating expenses is what distinguishes cost of goods sold from every other expense.
| Line | Amount |
|---|---|
| Revenue | $420,000 |
| Cost of goods sold | ($252,000) |
| Gross profit | $168,000 |
| Operating expenses | ($121,000) |
| Operating income | $47,000 |
Scroll sideways to see all columns.
Gross profit is reported as $168,000, which represents a gross margin of 40%. Gross profit exists as a reported figure only because cost of goods sold is separated from operating expenses. Where every expense is grouped together, operating income is still reported as $47,000, and the ability to identify whether the business is being compressed on its costs of production or on its overhead is lost. Compression on costs of production and compression on overhead are different problems and are addressed by different measures.
The same distinction is what separates revenue from profit as measures of business performance, and that distinction is set out in revenue versus profit.

The test that classifies a cost correctly
A single test classifies most costs correctly, and that test is whether the cost would still be incurred during a period in which the business sold nothing at all.
A cost that would not be incurred in such a period is a direct cost and belongs within cost of goods sold. A cost that would still be incurred in such a period is an overhead cost and belongs within operating expenses. Rent falls due whether or not a single unit is shipped during the period. Raw materials are not consumed where nothing is produced during the period.
| Classified within cost of goods sold | Classified within operating expenses |
|---|---|
| Raw materials and components | Rent and utilities |
| Merchandise purchased for resale | Administrative salaries |
| Direct labor applied to the product | Marketing and advertising |
| Freight in on goods received | Office supplies |
| Manufacturing supplies consumed in production | Insurance and professional fees |
| Depreciation of production equipment | Depreciation of office equipment |
| Merchant processing fees, in many arrangements | Back office software subscriptions |
Scroll sideways to see all columns.
The costs that sit on the line

A small number of costs are genuinely ambiguous, and competent accountants classify those costs differently.
Freight in, meaning the amount paid to receive inventory into the business, forms part of cost of goods sold because freight in forms part of the cost of the goods. Freight out, meaning the amount paid to deliver goods to the customer, is ordinarily classified as a selling expense. Some businesses classify freight out within cost of goods sold in order to keep delivered margin visible, and either classification is defensible. Applying one classification in one period and the other classification in the following period is not defensible.
Payment processing fees scale directly with sales volume, which supports classification within cost of goods sold, and payment processing fees are also a cost of collecting money rather than a cost of the product, which supports classification within operating expenses. One classification should be selected at the outset and applied consistently in every subsequent period.
Owner compensation is direct labor to the extent that the owner personally produces the product. Most small businesses classify all owner compensation within operating expenses, and that treatment quietly overstates gross margin.
Software is classified according to the function that the software performs, so that a subscription operating the production line is arguably a direct cost while the accounting system used to keep the books is not a direct cost.
A classification that is applied consistently is more useful than a classification that is theoretically perfect. Gross margin is read as a trend across periods, and a trend constructed on a definition that changed partway through the year reports nothing reliable.
The formula
Beginning inventory plus purchases during the period minus ending inventory equals cost of goods sold.
Consider a business that begins the quarter holding inventory of $38,000, purchases a further $96,000 of inventory during the quarter, and holds inventory of $41,000 at the end of the quarter. Beginning inventory of $38,000 plus purchases of $96,000 minus ending inventory of $41,000 produces cost of goods sold of $93,000.
The formula makes a point that is frequently missed, which is that cost of goods sold measures what was sold during the period and does not measure what was purchased during the period. Purchasing $96,000 of inventory does not create $96,000 of expense. The cost of purchased inventory is reported on the balance sheet as an asset until the inventory leaves the business, and the cost is transferred to the income statement only at the point of sale. A business can therefore report a heavy month of purchasing alongside a light month of cost of goods sold.
The equivalent category in a service business

A business that sells hours rather than physical goods reports the equivalent category under the caption cost of services or cost of revenue. Cost of services contains the compensation of the people who deliver the work, the amounts paid to subcontractors, and costs incurred specifically for individual projects. Sales costs, administrative costs and marketing costs remain below the gross profit line.
An agency that bills $400,000 and pays $240,000 to the people who produce the work reports a gross margin of 40%, and that figure is at least as useful as the equivalent figure reported by a manufacturer, because that figure reports what remains available to cover every other cost of the business.
The journal entry
Under a perpetual inventory system, a sale generates two entries. One entry records the revenue arising on the sale, and a further entry transfers the cost of the goods out of inventory.
| Account | Debit | Credit |
|---|---|---|
| Cash or accounts receivable | $1,200 | |
| Sales revenue | $1,200 | |
| Cost of goods sold | $740 | |
| Inventory | $740 |
Scroll sideways to see all columns.
Under a periodic inventory system no entry is recorded at the time of sale. Cost of goods sold is calculated once at the period end using the formula set out above, after a physical count has established the amount of ending inventory.
The cost of misclassifying a single line
Consider delivery driver wages of $30,000 that are recorded within operating expenses and that should have been recorded within cost of goods sold. Net income does not change by a single dollar. Gross profit falls from $168,000 to $138,000, and gross margin falls from 40% to 32.9%.
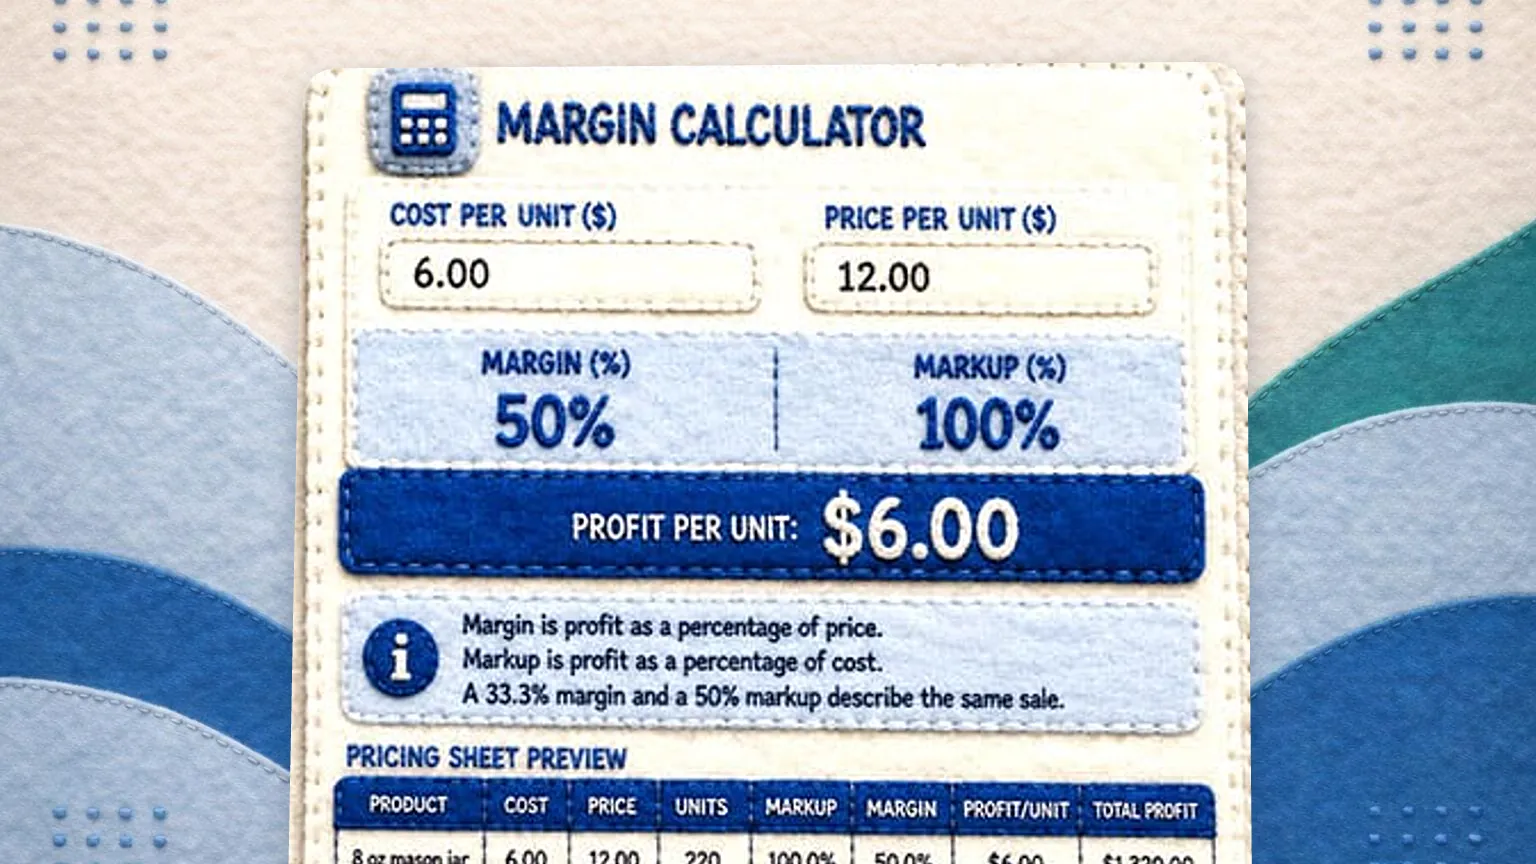
That difference matters because gross margin is the figure used to set prices, the figure a lender compares against industry benchmarks, and the figure that indicates whether a price increase of 5% would be generous or overdue. A margin figure that is understated by seven percentage points will direct the business toward the wrong decision on every occasion the figure is consulted. The effect of a margin change on real figures can be modelled directly in the margin calculator.
If you are not sure which side of the line a cost belongs on, the honest answer is that most accounting systems will happily let you get it wrong and say nothing. GlassJar keeps direct costs and overhead in separate account ranges and reports gross margin on its own, so a misclassified line shows up as a margin that moved rather than a number nobody questioned. See how it works.
Frequently asked questions
Is cost of goods sold an expense?
Cost of goods sold is an expense and reduces profit. Cost of goods sold is reported separately above gross profit rather than being grouped with the operating expenses reported below gross profit.
Is cost of goods sold an asset or an expense?
Cost of goods sold is an expense. The related inventory is reported as an asset for as long as the inventory is held, and the cost becomes cost of goods sold at the point the inventory is sold.
What type of account is cost of goods sold?
Cost of goods sold is an expense account carrying a normal debit balance. Cost of goods sold is a temporary account and is closed to retained earnings at the end of the year.
What is the difference between cost of goods sold and operating expenses?
Cost of goods sold contains costs that vary with what is produced or sold. Operating expenses contain the costs of operating the business irrespective of sales volume, including rent, administrative salaries and marketing.
Does a service business report cost of goods sold?
A service business reports the equivalent category, ordinarily captioned cost of services or cost of revenue, containing the direct labor and the project costs incurred in delivering the work.